A bill before the National Assembly would add production tax credits for books and electronic publications. The proposal asks whether the earliest, least visible stage of the content pipeline should receive the same kind of support as webtoons and video.
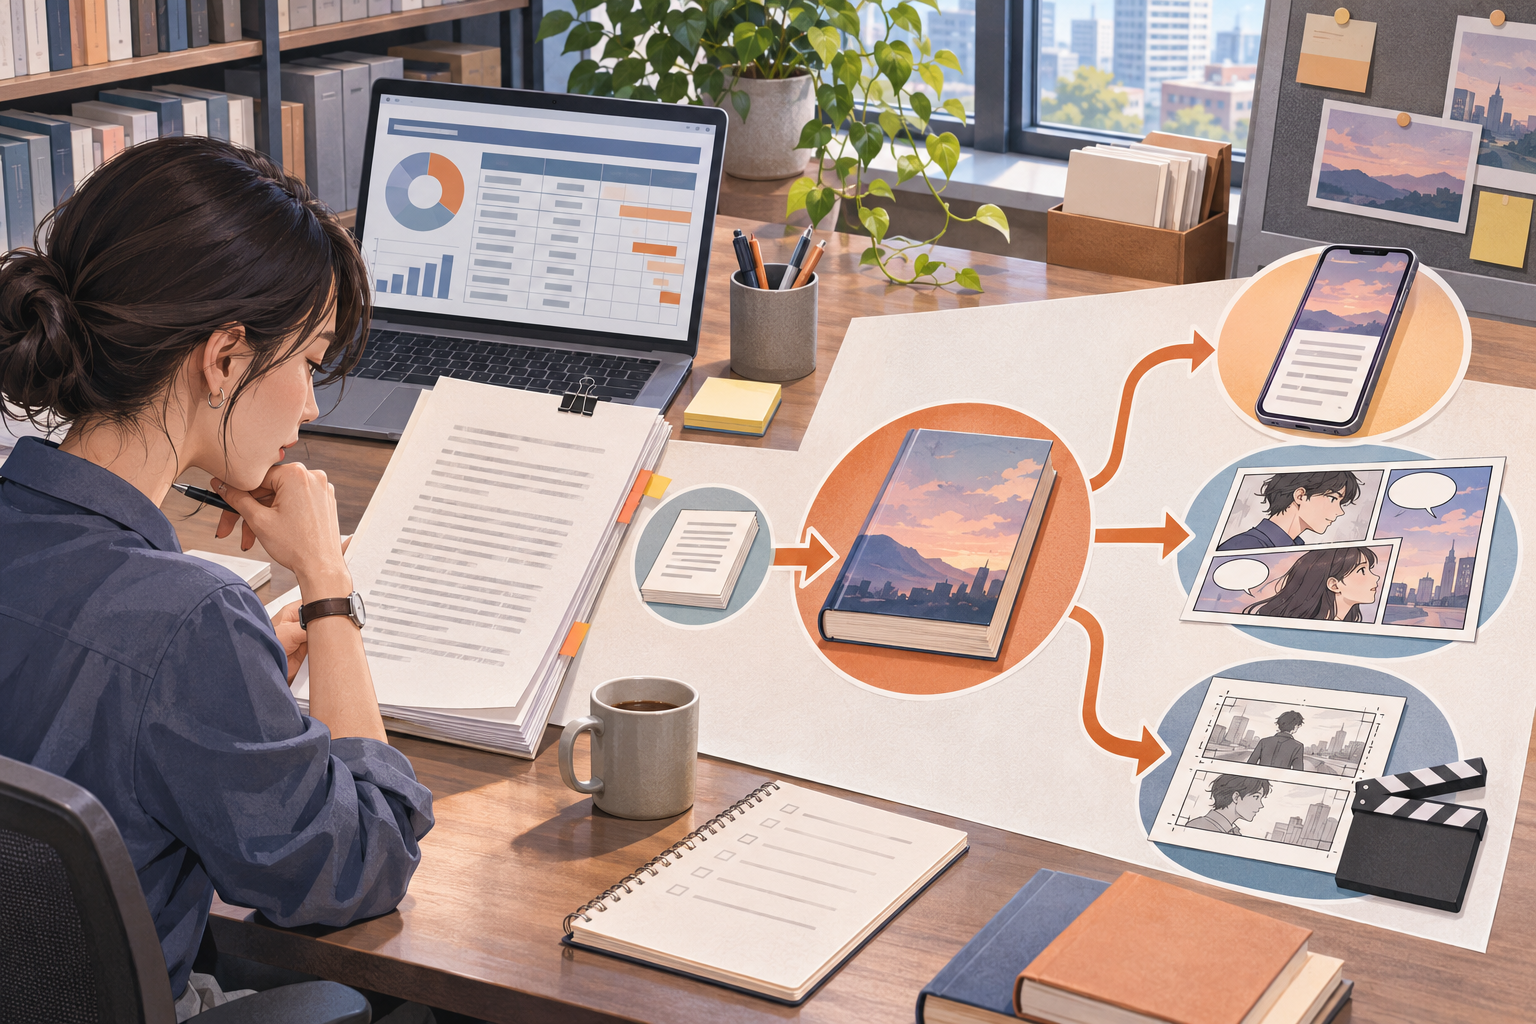
Korean policy often celebrates the last, most visible step of a content success: the drama, film, webtoon or game that reaches a large audience. A new bill asks the government to support an earlier step—the book or electronic publication from which other work may grow.
The proposed amendment to the 조세특례제한법 (Restriction of Special Taxation Act), introduced on October 28, would create a production-cost tax credit for qualifying publications and electronic publications. It has been referred to the National Assembly’s Strategy and Finance Committee. It has not passed.
That last point is important. This is an active legislative proposal, not a benefit publishers can claim today.
What the bill proposes
The bill would establish a basic credit equal to 10 percent of qualifying production costs. Small and medium-sized companies would receive 15 percent. A project meeting additional conditions—such as a required share of production spending incurred in Korea—could receive an additional credit at the same rate.
The exact range of qualifying publications and costs would be set through subordinate rules if the bill becomes law. The proposal excludes some categories, including foreign publications and certain study guides or test-preparation works. It would run through the end of 2029 under the current text.
The bill also tries to prevent double counting. If the same cost could qualify under the video-content or webtoon production credit, a company would have to choose one program.
This is not a grant paid before a book is made. A tax credit reduces tax owed after qualifying costs are incurred and the relevant conditions are met. Its value therefore depends on a publisher’s tax position, accounting and ability to finance production in the first place.
Why publishing wants parity
Korea already offers production-cost support through the tax system for video and webtoon content. Publishers and webnovel writers argue that the text layer has been left out even though it supplies stories, research and rights that later move into those sectors.
At a National Assembly forum on November 2, representatives from publishing and webnovel organizations pressed for the credit. Their case was not only that books deserve cultural recognition. They framed edited, verified text as production infrastructure for adaptations and for an artificial-intelligence economy increasingly hungry for reliable language material.
That argument can become inflated if every book is treated as a future franchise. Most books will not become dramas or webtoons, and adaptation potential is not the only reason to publish them. The stronger case is simpler: editing, design, author advances, rights work, translation and distribution all require investment before demand is known.
A production credit would lower part of that risk for firms able to use it.
The consequence for creators is in the budget
Tax policy is distant from the reading experience until it changes which projects can be financed.
For a publisher, lower effective production cost could support a larger print decision, more editorial time, a translation sample or a new author whose sales are uncertain. For a webnovel producer, the debate raises a boundary question: whether serialized digital text should be recognized as publishing content when tax rules divide books, webtoons and video into separate categories.
None of those outcomes is guaranteed by the bill. A company could use savings without increasing author pay or editorial investment. Large publishers may be better positioned than small presses to document expenses and wait for a tax benefit. Detailed eligibility rules will decide whether the policy reaches the projects that face the greatest financing constraints.
That is why the percentage is only the first question. Readers and creators should also ask which labor counts, whether translation and overseas distribution qualify, how independent publishers access the credit and what evidence will show that the measure increased production rather than subsidized work that would have happened anyway.
A book is not only raw material
The bill’s supporters emphasize publishing as “source content.” The phrase is strategically useful, but it can also reduce a finished book to a preliminary asset waiting for a more lucrative form.
A novel, essay, scholarly work or webnovel does not need an adaptation to justify investment. Its reading public is already an audience. Good policy should recognize both functions: a publication can be complete in itself and part of a larger rights economy.
The proposal is now in committee review, where its cost, exclusions and relationship to existing credits can change. Until passage and implementing rules, publishers should not treat the headline rates as settled support.
The larger decision is already clear. Korea has built tax incentives around the content people see on screens. The National Assembly is now considering whether the text people read before—and sometimes instead of—the screen belongs in the same production system.
Sources
- Restriction of Special Taxation Act amendment, bill No. 2222226, bill data and National Assembly source links; introduced October 28, 2026.
- National Assembly forum on a publishing-content production tax credit, November 2, 2026.
- Ministry discussion of publishing policy and tax-credit legislation, September 16, 2026.